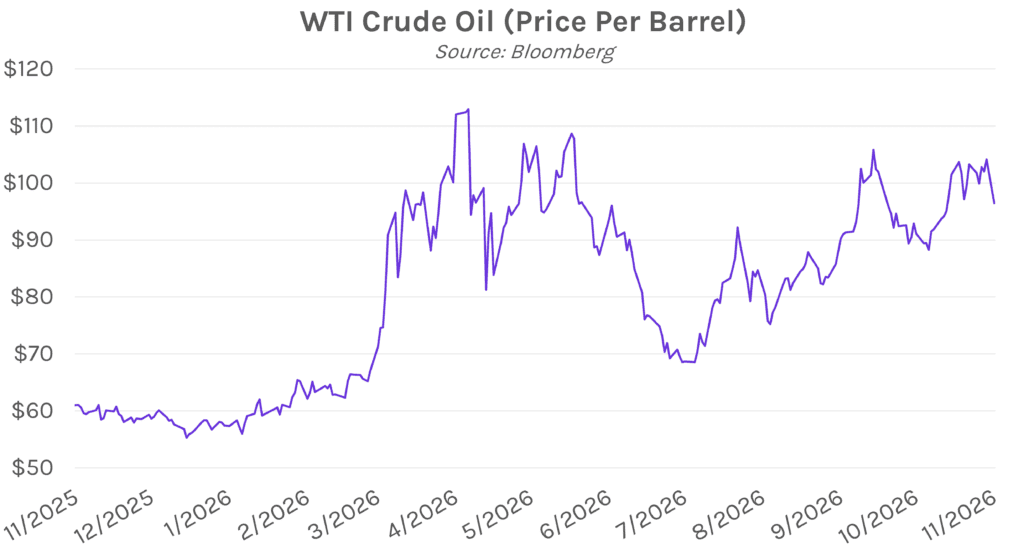
Yields narrowly mixed on hopes for US-Iran peace talks. The yield curve flattened today as optimism for diplomatic progress between the US and Iran provided relief for oil prices and energy-driven inflation concerns. WTI futures closed over 7% lower around $96 per barrel. The 2-year yield closed 1bp higher at 4.59%, while the 10-year yield closed 2 bp lower at 4.91%. Meanwhile, equities fell as chipmaker stocks continued to sell off, with the S&P 500 and NASDAQ closing 0.51% and 1.07% lower, respectively.
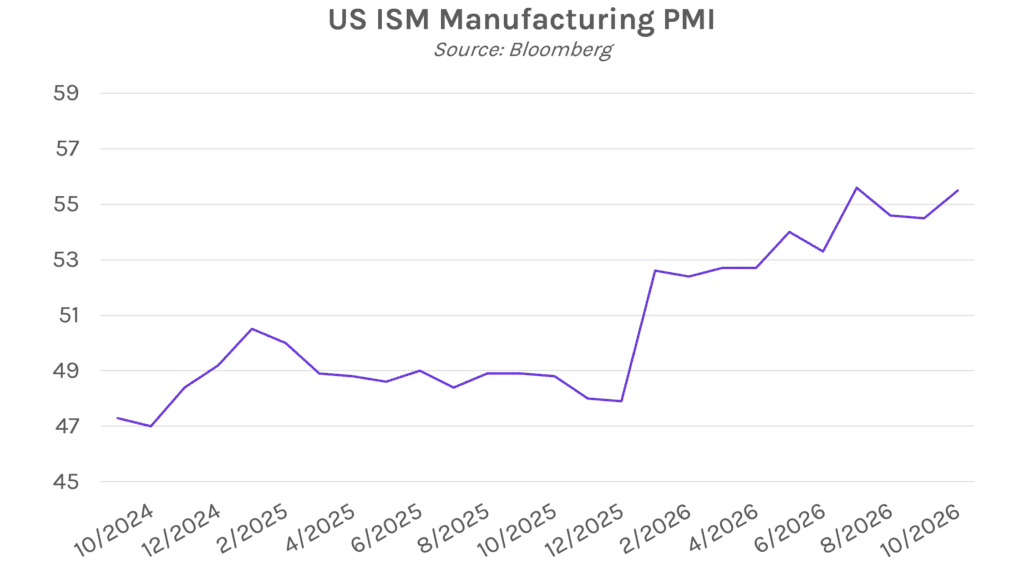
US production growth hits five-year high. ISM Manufacturing PMI rose to 55.5 in October, above expectations and the prior month’s 54.5, marking the tenth straight month of growth in the sector and the second-highest reading in four years. Production drove the increase, with the ISM production index reaching 59.0, its highest level since November 2021 and up from 56.7 in September. Demand also stayed strong, with a measure of new orders reaching 55.5, the highest level since July. The manufacturing gain reflects continued capital expenditure on AI and industrial equipment, along with strong consumer spending as twelve of fifteen industries expanded in October, led by electrical equipment and computer and electronic products.
US-Iran negotiations continue ahead of midterms. Peace talks between Washington and Tehran continued over the weekend, reportedly leading to progress but no breakthroughs. Negotiations centered on the seven-point plan Iran proposed in September, despite President Trump’s prior rejection of the agreement. The draft has reportedly been condensed and could be implemented within two days of signing, aimed at reopening the Strait of Hormuz and ending US blockades of Iranian ports, but without addressing Iran’s nuclear capabilities. Russia and China expressed concern that the US may resume strikes following tomorrow’s midterm elections, with both nations speaking out today against further military action.