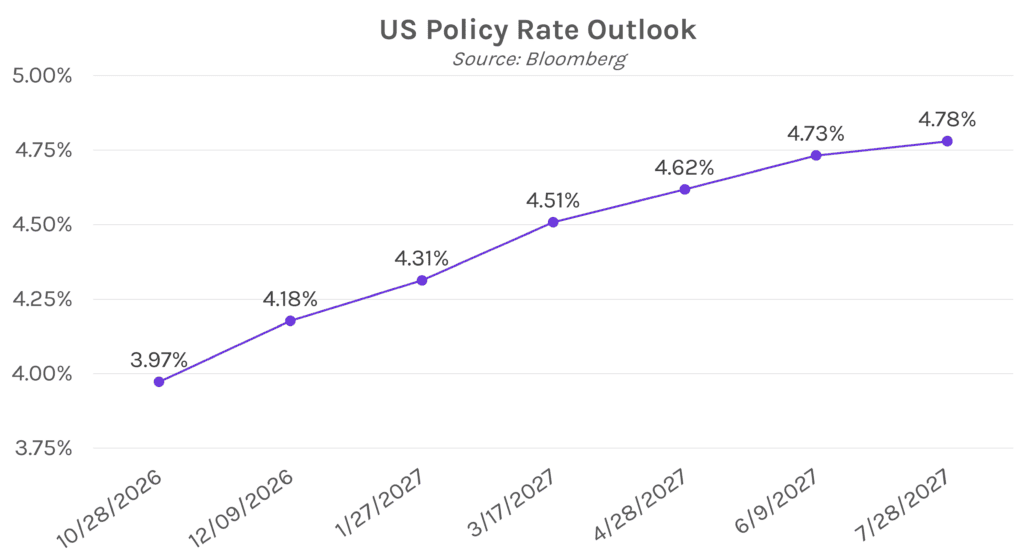
Yields edge higher as PCE comes in soft. Treasury yields initially declined in response to this morning’s softer-than-expected PCE print, though the move reversed over the remainder of the session as inflation concerns remain in focus. Futures markets now see an October rate hike as ~37% likely and a December rate hike as ~81% likely. The 2-year yield closed 1bp higher at 4.89%, and the 10-year yield closed 5 bps higher at 5.29%. Meanwhile, equities were mixed, with the S&P 500 closing 0.25% lower and the NASDAQ closing 0.24% higher.
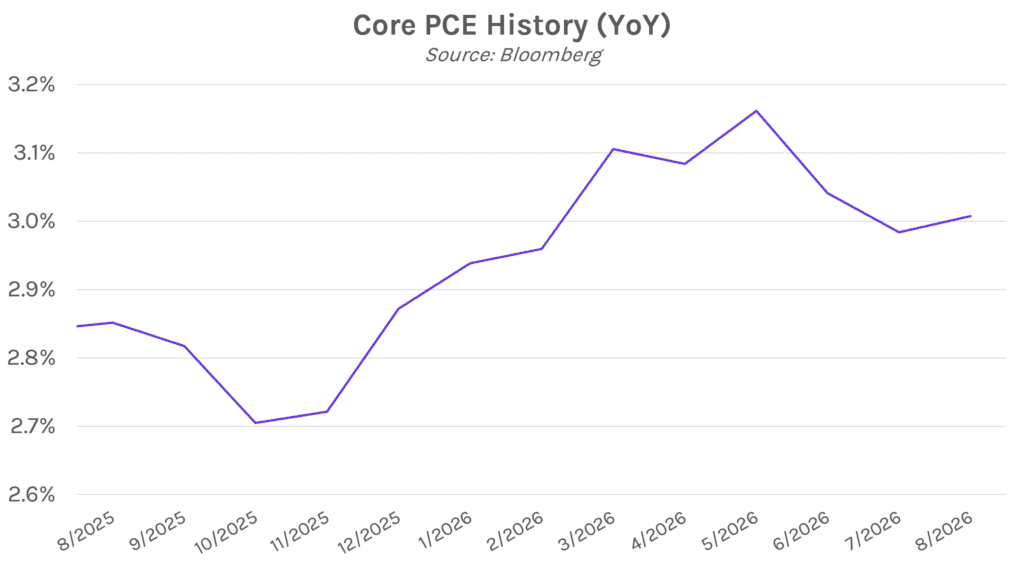
Inflation data comes in cooler than expected. August PCE data released today showed broad-based softening in inflation, with the headline figure coming in at 0.3% MoM and 3.4% YoY, in line on a monthly basis and below expectations of a 3.7% annualized increase. The prior month’s level was also revised down from 3.7% to 3.4% YoY. Core PCE, which excludes food and energy, was also softer than expected, landing at 0.2% MoM and 3.0% YoY, compared to forecasts of 0.3% and 3.3%, respectively. July’s core PCE figure was revised lower to 3.0% from 3.3%. Today’s figures are still above the Fed’s 2% inflation target; however, the cooler readings take some pressure off the Fed ahead of the October FOMC meeting.
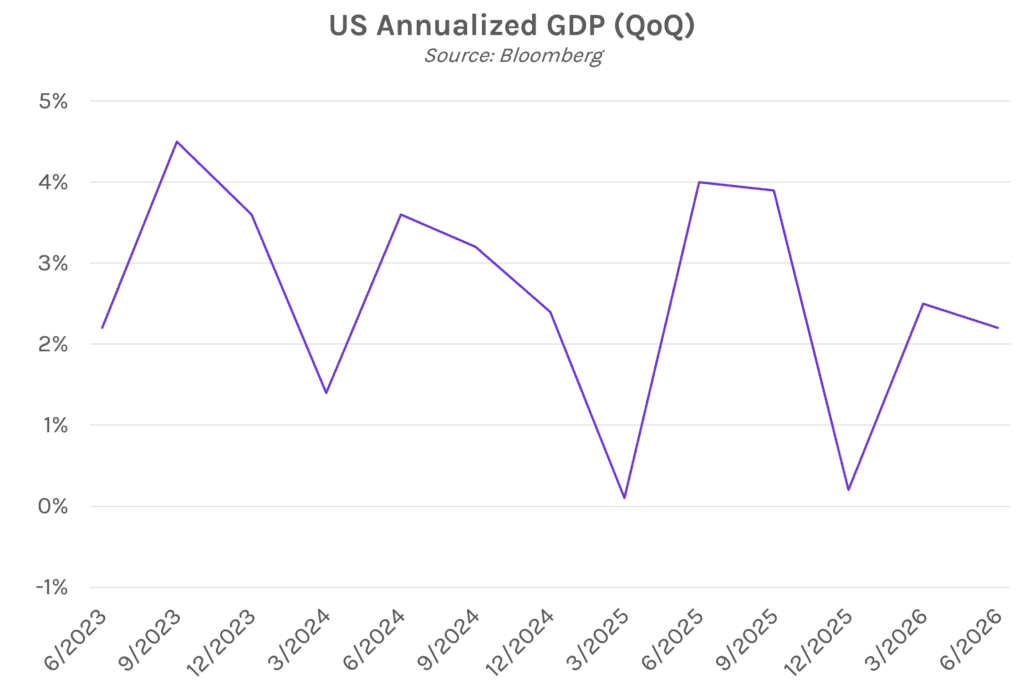
US GDP posts surprise Q2 advance. The US economy grew at an annualized rate of 2.2% in the second quarter, a surprise advance from the preliminary estimate of 1.5%. The upward revision reflects strong business investment in AI, consumer spending, and government outlays. Personal consumption increased 3.8%, rising at the fastest pace since 2024 and up sharply from 0.7% in the first quarter. Business equipment spending also posted double-digit growth. The GDP price index increased 6.1%, below expectations of 6.4%.